cross posted from citizenship solutions
by John Richardson
I suggested to John that some might not understand why a similarity between OVDP and the Transition Tax was being made. He asked me to introduce the post to make sure it was clear that the U.S. government has demonstrated that confiscation is the name of the game (NOT tax).
Some of you may wonder why a connection is being made between the OVDP program and the Transition “Tax.” The reason is very simple. We need to change the language. We need to call it what it really is. In the beginning, people were too frightened to understand what the OVDP really was. It took years before it was clear it was nothing less than confiscation. Fortunately, we knew prior to the passage of the Tax Jobs Cut Act that the Transition “Tax” was a blatant confiscatory provision.
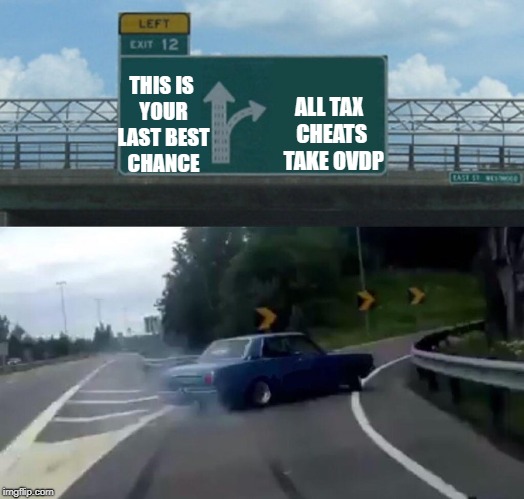
The “Offshore Voluntary Disclosure Program.” An “amnesty” program. Nine years and many destroyed lives have exposed it for what it really was. No one could really have considered it “voluntary.” The IRS and the tax compliance community certainly presented as one’s only option. In 2011, we did not have the advantage of what we know now; the limitations of being discovered, the extremely difficult/unlikely ability of the IRS to collect. People who had no tax liability among other atrocities, were fined from 20 – 27.5% of their assets. There was no taxable event. This revolved around not filing a piece of paper. FBAR. An appropriate term used was “The FBAR Fundraiser.” Another word would be confiscation. IOW, OVDP was NOT about TAX.
Some words have powerful associations. Sometimes those associations grow into clichés. We are all familiar with the association that anyone who has left America is rich has done so to avoid tax. We have been working at this since late 2011. Seven years. No amount of trying to educate via comments on online articles etc. has put a dent in this erroneous and damaging perception. Recently, some of us have started replacing “citizenship taxation” with “non-resident taxation.” Non-resident taxation describes what it really is and dissociates from the idea that a patriotic citizen (American) should pay it. It appeals to the notion that reasonable people accept i.e., that one pays taxes (only) where one lives. It may take time but the value of changing the language in this situation, is obvious.
To refer to this new requirement as a “tax” is to immediately justify it as being reasonable. Take the Canadian government for example. It’s position is that the U.S. has the right to tax it’s own citizens and that Canada has no business interfering with that. Thus the IGA. Nevermind that the majority of the people affected are Canadian citizens and residents FIRST.
So what’s wrong with the term “Transition Tax?” As we all know, any expat with a “foreign” corporation will be unable to transition to a territorial system as will major multinationals . So to call it a “transition” is completely erroneous. As for “tax”, a general notion is that a tax is connected with delivery of services or benefits i.e., there is some relationship between the exchange of income for services. It is nothing short of bizarre to levy a 30-year retroactive tax on a group of people who were not residents, nor receiving anything in exchange for surrendering a considerable portion of what is primarily, their retirement pensions.
A phrase John has used repeatedly to describe the Transition “Tax” is “the confiscation of the retirement pensions of the citizens and residents of other countries.” That’s what it really is. Like the OVDP, it is a punitive tool that destroys the lives of long-term expats. We need to get that message across.
****
by John Richardson
Introduction
This is the fifth in my series of posts about the Sec. 965 Transition Tax and whether/how it applies to the small business corporations owned by tax paying residents of other countries (who may also have U.S. citizenship). These small business corporations are in no way “foreign”. They are certainly “local” to the resident of another country who just happens to have the misfortune of being a U.S. citizen.
The purpose of this post is to argue that (as applied to those who do not live in the United States) the transition tax is very similar to the OVDP (“Offshore Voluntary Disclosure Programs” which are discussed here. Some of initial thoughts were captured in the post referenced in the following tweet:
The first reason (of many) why the @USTransitionTax, if applied to individual U.S. shareholders who are #Americansabroad, is analogous to #OVDP AKA the “Offshore Voluntary Disclosure Program" https://t.co/XmQRyFYS5Q via @CitizenshipTax
— John Richardson – Counsellor for US persons abroad (@ExpatriationLaw) March 20, 2018