
JC posts:
VERY IMPORTANT! You want a change, sign the petitions. You do not want a change, do nothing.
TTFI PETITION.
JC posts:
VERY IMPORTANT! You want a change, sign the petitions. You do not want a change, do nothing.
TTFI PETITION.

The issue of tax residence has gained so much attention since the “crackdown” on non-resident US Persons began in 2009. It is commonly understood that you pay taxes to the country/state/city-town that you reside in. (For an interesting comparison of differences between countries please see this incredible list compiled by the OECD). It simply does not occur to anyone that they would be required to pay taxes to a foreign government.
However, the United States claims jurisdiction due to citizenship. One does not even have to have touched foot in the U.S., according to U.S. law. Of course, due to the viciousness of the U.S. “FBAR Fundraiser” many people began to resist whether of anger or fear.
Not much has changed* , in spite of all the factors that have contributed to this debacle (and debacle it is, what could one expect when a country tries to take what is someone else’s, based on an idea of fake residence?).
For a detailed discussion concerning the determination of tax residence and related factors, please see here.
In this interview, John Richardson speaks with Olivier Wagner about tax residency and how a seemingly simple concept has become so terribly important in the 21st century.
In a #FATCA and #CRS world – the most interesting thing about a person is where has @taxresidency ESPECIALLY when he has > one. @Expatriationlaw interview with CPA @1040Abroad: ‘Episode 1 of: "A Tax Residency Primer"- Tax, Residency and #TaxResidency" https://t.co/6swfQmJO7i
— John Richardson – Counsellor for US persons abroad (@ExpatriationLaw) August 8, 2018

NB: STAY TUNED – a 7-part video on the Transition Tax, with
John Richardson & Karen Alpert are available here .
NB: For anyone with time to spare/the interest/needing specifics to make the point regarding the “intention” of the law, here are some of the relevant House/Senate hearings and/or documents:
Oct 3, 2017 Full Committee Hearing -Senate Finance
Nov 6 – 9, 2017 H W & M Markup
Nov 13, 2017 Open Executive Session to Consider an Original Bill Entitled the Tax Cuts and Jobs Act Sessions also continued Nov 14, 15, 16 with videos at the page)
Supporting Document Markup – Senate Finance Committee
*******
Another day, another set of articles and comments where the #TransitionTax & #GILTI are being stuffed down the throats of expatriates who have their own small corporations. The proliferation of articles on this issue, all proclaiming the U.S. can now inflict a deeper cut into the retirement savings of non-residents, is infuriating. The first two articles at least expressed the idea that these provisions do not might affect non-resident U.S. taxpayers.
Max Reed , posted on November 3, 2017:
As part of this transition, the new rules impose a one-time 12% tax on income that was deferred in a foreign corporation. Although perhaps unintentional, since US citizens will not benefit from a territorial model, the new rules impose a 12% tax on any cash that has been deferred since 1986.
Kevyn Nightengale, posted on November 10, 2017 (I have not included the updated comments because this is what we saw at that time):
This provision was not designed to catch individuals (I think), and certainly not Americans abroad – they are collateral damage. it’s incredibly unfair.
When I saw the House version, I expected that individuals would be exempted after a sober second (or third) thought. Or at least individuals living abroad would be exempted. But seeing a parallel provision in the Senate version makes me expect the worst.
Seems fairly obvious that the biggest clue that the #TransitionTax IS NOT meant to apply to small CFC’s is that they are not “transitioned” from a worldwide system to a territorial one. This is so basic it is hard to believe nobody just calls these people out on this. How many tax professionals watched all of the House/Senate hearings? Many of us did, all hoping to hear that the move to territorial would include individuals; or at least some mention of us. There simply was nothing to suggest that this tax applied to anyone except large multi-national corporations.This provides the context in which the law was conceived. It should be considered just as thoroughly as the plain reading that professionals claim catches expats in the net. Just exactly who is really making the law here?
Continue reading
UPDATE Our Stories
It’s Cruel how we Have had to Give up our Right to Return
A Dual who Managed to Relinquish!
I Renounced – for Human Rights, for Privacy Rights, & for Showing Respect for my Husband’s Privacy
I Lost Hope
I did not Leave America, the U.S. Government Left me
I Feel Cheated by my ex-Country who Treats its Citizens in This Way
How I Became Canadian and Ended up Renouncing US Citizenship
Last Generation American
Why won’t the USA Graciously let its People go?
*******
I would like to create a section on the Citizenship Taxation website that is devoted to the stories of those who have renounced/relinquised. The primary purpose is to demonstrate a different focus than that of trying to keep it, hoping for change in the political process, etc. Hopefully it would include what it felt like during the period of deciding (the OMG moment + any particular stresses that pointed you in that direction), could include the actual appointment(s) at the Consulate, the aftermath, family reactions, etc. Whatever you feel would be meaningful to communicate…….
Real names are not required. All requests for privacy concerning email, name etc will be strictly respected/followed.
Please email to:
information at citizenshiptaxation at dot ca
Thanks!
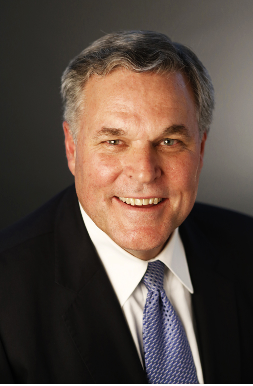
Politico announced Trump’s nomination Of Charles P. Rettig, including the following excerpts:
Rettig, who specializes in settling complex tax disputes between his taxpayer clients and authorities like the IRS, known as tax controversies, has for more than three decades represented clients before the IRS, the Justice Department, state tax authorities and other jurisdictions.
Rettig is no stranger to the Washington tax policy community. Many IRS officials would be familiar with him because of tax litigation in which he’s been involved.
Rettig’s nomination would break a nearly two-decade practice of naming commissioners from the general business world, a trend that began after the IRS Restructuring and Reform Act of 1998. Prior to that, commissioners generally had tax backgrounds.
Continuing with the conversation from Media & Blogs thread, I see many mentions of the fact that his firm represented some 100 UBS clients (which may be why some of his articles concern the OVDP). I am trying to locate some actual court cases but the site that keeps coming up in references seems to be down. He also clearly, is respected for his work representing clients by his peers:
Rettig would also oversee the implementation of tax reform. Rettig has been a friend and mentor to many of us in the tax controversy bar over the years, and we are encouraged by the selection of someone from the private bar to the post.
Given he is a tax litigator, I don’t expect he would support a change to RBT (hope I am wrong about that) but some of his comments certainly suggest he understands what has happened and that our situation is very different from that of U.S. residents with foreign accounts.
Forbes IRS FBAR Streamlined Procedures Revisited, Am I Non-Willful
If, as some believe, the Streamlined Procedures are being used to entice unsuspecting taxpayers into placing their head onto the FBAR chopping block, the government should be held accountable. However, if, as most believe and our experience seems to support, the Streamlined Procedures were designed to provide not quite willful taxpayers an opportunity back into compliance through a simplified and expedited process, the IRS should respect the vast majority of Streamlined submissions (and requests for transitional treatment) and move on.
Forbes IRS FBAR Voluntary Disclosure Program Taxpayer Interviews
It should be anticipated that the IRS will pursue examinations of the amended returns of taxpayers residing in the United States in some manner. It remains uncertain whether the IRS would or could effectively pursue those residing outside the United States in any realistic manner. It should also be acknowledged that there remain viable alternatives to the OVDP, including the voluntary disclosure practice of the IRS set forth in Internal Revenue Manual (IRM) 9.5.11.9 [see Example 6(A)], Section 4.01 of the Criminal Tax Manual for the U.S. Department of Justice, and Section 3, Policy Directives and Memoranda, Tax Division of the U.S. Department of Justice.
Certainly, given the complexities of the Internal Revenue Code, other relevant statutes and life in general, many of the indiscretions associated with an income tax return or FBAR are anything but willful or intentional and definitely not fraudulent or criminal in nature. In these situations, an interview of the taxpayer and/or their return preparer can lead to an extremely quick and reasonable resolution.
Many, many articles penned by Mr. Rettig are available via SSRN and listed here.
Bubblebustin asked for this post to be based upon this paper. Unfortunately the most we can offer is the link and a few excerpts. Strongly suggest everyone read this particular article- Why the Ongoing Problem with FBAR Compliance? from the Journal of Tax Practice & Procedure, August-September 2016, published by CCH, a part of Wolters Kluwer.
A major point in the article is when government is trusted, is seen as legitimate, compliance tends to be a result. It probably does not help that the IRS emphasizes submissions coming from OVDP and Streamlined will be examined “in an effort to uncover leads for criminal prosecutions.” Mr. Rettig is also aware that eighty percent of non-resident filers will have no U.S. Tax Liability. Though again, that is a reference to income tax and does not cover some of our worst grievances.
Potential government actions should consider the
impact on those six-plus million U.S. people (and their
advisors) sitting in the bleachers domestically or in various
foreign countries trying to determine how best to pursue
some form of voluntary compliance, expatriation or to
possibly just continue sitting in the bleachers … “History
repeats itself because no one was listening the first time.”

cross-posted from citizenshipsolutions
Update January 2018: This post has been updated with some new links and discussion.
Part I is here.
*****
We are witnessing what McGill law professor Allison Christians once referred to as the “Story of The Century“. To borrow from Professor Christian’s post:
The US is right now imposing enormous penalties and unleashing general chaos on people living in other countries with US citizenship, both by newly enforcing long-ignored rules and by layering on top of these rules a new and more draconian layer of enforcement. The chaos comes in the form of fear-inducing, devilishly complicated and duplicative paperwork, and penalties, most of all penalties, and it is being piled on to millions of people around the world, many of whom, like Cruz, are very possibly only beginning to understanding that citizenship status is mostly conferred upon rather than chosen by individuals.
Ted Cruz should consider himself very lucky. The Canadian citizenship he claims he didn’t realize he had, doesn’t carry any punishment IN CANADA for his failure to recognize it. Moreover renouncing Canadian citizenship, if he really intends to follow through on that promise, will be relatively simple, cheap, and painless other than any damage (if any) to his US political career. (Interestingly Australian Green Party Senator Larissa Waters was forced to resign because she was born in Canada and still (although she was unaware of it) held Canadian citizenship.
Not so if Mr. Cruz he had lived his life in Canada with his current apparent dual status. US citizens abroad now understand that discovering ties to the US means discovering a world of obligations and consequences flowing from citizenship that one was expected to know and obey. Ignorance of the law being no excuse, the punishments range from the merely ridiculous–many times any tax that would have ever been due–to the infuriating: life savings wiped out and many future tax savings sponsored by your home government, such as in education or health savings plans, treated as offshore trusts and therefore confiscated by the US. Moreover there is no ready escape hatch for the newly discovered and unwanted US citizenship: five years of full tax reporting compliance must be documented, appointments must be made with officials, fees must be remitted, interviews must be conducted, and in some cases exit taxes must be paid. If some in Congress get their way, renunciation could even mean life-time banishment from the US someday soon.
In the grand scheme of things Ted Cruz’s citizenship is a non-story. But for what it illustrates about citizenship-based taxation, it could be the story of the century.
The Debate – Taxation Based On The “immutable Characteristic of Place of Birth”
Continue reading
TaxProf Blog informs us that National Taxpayer Advocate Nina Olson’s 2017 Annual Report to Congress has just been released. The latest report contains similar criticisms of diaspora abuse and suggestions for improvement which the IRS & Congress ignored last year and every previous year since 2012 2011. Criticisms of FATCA and mailing delays have been condensed and toned down since last year. Criticisms of passport revocation have been expanded. That stuff is more or less business as usual; see below the fold for details.
However, there’s one new section which makes this worth a separate post: discussion of penalties for not filing international information returns (Vol. 1, p. 314). Ms. Olson managed to get her hands on some interesting data and examples: in particular, she found out that the IRS collected nearly twenty-three times as much in penalties on failure to file Form 3520 in 2016 as in 2013. (I wonder how much of this came from those 48,000 “Streamlined” participants.)
| Form1 | Legal basis for penalty |
Penalty type | Net penalty after abatement | Growth in penalty revenue1 |
|
|---|---|---|---|---|---|
| 2013 | 2016 | ||||
| 5471 (Cat. 4) 8865 (Cat. 1) |
§ 6038 | Initial | $7,587,151 | $20,364,300 | 168% |
| Continuation | $3,576,416 | $35,991,336 | 906% | ||
| 5471 (Cats. 1/2/5) 8865 (Cats. 2/3/4) |
§ 6679 | Initial | $30,000 | $60,000 | 100% |
| Continuation | N/A2 | $2,671,935 | N/A | ||
| 3520 | § 6677 | Initial | $30,800,327 | $702,187,004 | 2,180% |
| Continuation | N/A2 | $6,645,580 | N/A | ||
| Total penalties (comparable categories only)3 |
$41,993,894 | $758,602,640 | 1,706% | ||
|
Adapted from Figure 2.7.1, “International Penalties Assessed and Abated in the Aggregate in FYs 2013 and 2016”. Penalties from Form 5472 are excluded. Notes: 1. Form name and penalty growth not in original; any errors in those columns are my own. |
|||||
The actual recommendations in the new section are uninspiring. Ms. Olson doesn’t comment on the growth in penalties, nor inquire as to the reasons behind it. Nor does she suggest reversing the massive hikes in statutory level of those “offshore” penalties over the past two decades, which have left members of the diaspora in fear of bankruptcy for foot-faults on paperwork about local assets (while Homelanders with similarly-situated local assets face penalties proportionate to actual tax, or even no penalties at all because no equivalent paperwork exists for them). She only asks Congress to give the IRS consistent authority to waive penalties for reasonable failures to file — right now, they can waive “continuation” penalties for some forms but not others. All well and good, except they’re barely using the penalty abatement authority they have anyway.
Dr. Karen Alpert of the University of Queensland will be presenting this paper at a conference of Melbourne next week:
The paper is based on her posts on investment constraints at the Fix The Tax Treaty Blog, but much more technical (I still found it very readable and useful as a layperson). It deals with both issues specific to Australia, such as superannuation, and issues affecting all US persons residing outside the US regardless of country. Karen is the founder of Australia’s FixTheTaxTreaty and a frequent commenter here at Brock.
cross-posted from Alliance for the Defeat of Citizenship Taxation
NB: While ADCT respects ACA’s positions and appreciates their lobbying efforts, this post in no way serves as an endorsement of their submission regarding RBT.
It bears repeating that no group approached Congress during the tax reform process and specifically requested RBT. Many chose to support RO’s effort (TTFI) assuming it more likely to succeed given Congress was clearly intent upon changing corporations to a territorial model.
ACA’s approach to RBT has been described by some as CBT with a carve-out (for those who are already compliant). It does not address the issues of Accidental Americans; becoming compliant for the express purpose of renunciation, etc.
TAX REFORM BILL AND AMERICANS ABROAD: WHAT HAPPENED? WHAT’S NEXT?

by Charles M Bruce
ACA’s Legal Counsel and Of Counsel to Bonnard Lawson-Lausanne
with contributions from Jonathan Lachowitz, Chairman, ACA, Marylouise Serrato,
Executive Director, ACA, and Jacqueline Bugnion, Former Director, ACA.
On the day President Trump signed the The Tax Cuts and Jobs Act (TCJA) , Mr. Bruce issued this letter (found on the ACA website).
EXCERPTS:
What happened?
Changes in the basic rules for Americans abroad were not made.
There are strong indications that Congress will soon return to the subject of tax law changes to make corrections in what was done and to address issues that were postponed. A couple of days ago Chairman Brady said, “I’m going to recommend that we do have some form of tax reconciliation in future budgets because there are still areas of the tax code I think . . . can be improved, including retirement savings, education, and streamlining,” Brady said. “And we had a number of good ideas from our members we weren’t able to accommodate. Plus, I think we’ll have to continue to modify the international code over time.”
What has not changed?
There are some serious problems.


