
Our Plaintiffs believe that the sacrifice of Canada’s sovereignty to a foreign state is wrong. Canadians can support Plaintiffs Ginny, Gwen, and Kazia by being a Witness in our FATCA IGA lawsuit. — If interested contact me at Stephen.Kish.Chair@adcs-adsc.ca
Is U.S. Congress REALLY planning to have our Canadian homes FBAR’d or 8938’d? Could this be the “last straw” that finally pushes U.S.-tainted Canadian citizens wanting to enter a lifetime of IRS compliance into total resistance?
I just noticed a comment from EmBee, who passed on to Brock a Maple Sandbox comment from “Anthony”, apparently a “Canadian lawyer”.
— Anthony actually says that the U.S. is planning to have homes of U.S.-tainted Canadian citizens FBAR’d (annual resale values etc. reported). Nonsense? Just a scare tactic?
If true, would this be that final straw that finally pushes affected, previously FBAR-obedient and quietly compliant Canadians into mass resistance, self-certification-without-permission-renunciation, and high anger?
Reminder: Solving U.S. Citizenship Problems – Toronto, Saturday, June 25, 2016

TORONTO CAN, Saturday, June 25, 2016
Are you or have you ever been, a U.S. Person? FATCA is looking 4 u. Toronto, Sat June 25, 1-3 pm 100 St. Joseph St. https://t.co/BcPYBqOCXj
— U.S. Expat Canada (@USExpatCanada) June 21, 2016
Have you received a FATCA letter or been warned of the consequences of being a U.S. person?
New this year in the U.S. assault on people and countries outside its borders, is the “second wave” of reporting – the “entity” reporting. This is nothing less than every financial entity – any corporation, non-profit corporation, your Canadian controlled-private corporation (CCPC), any fund with shareholders-is fair game for an associated financial lender, bank etc to ask:
“Who are your clients, shareholders? Are they, or have they ever been, U.S. citizens?”
If so, they need to fill out a US tax form. (W8-no withholding for non-US taxpayers or W9-for withholding on US taxpayers) to be kept on file with the bank.
My financial advisor indicated he now realized I had not exaggerated the extent of this U.S. interference in Canada. He now has to ask each and every new client, regardless of what they are buying,
“Are you, or have you ever been, a U.S. citizen?”
Utterly outrageous.
PLEASE register in advance by email to nobledreamer16 at gmail dot com
When: Saturday,June 25, 2016 1-3 pm
Where: 100 St. Joseph St., Toronto ON M5S 2C4 MAP
Admission: $20 payable in cash at the door
Who: John Richardson, B.A., LL.B., J.D. (Of the bars of Ontario, New York and Massachusetts), Toronto citizenship lawyer and Co-chair of the Alliance for the Defence of Canadian Sovereignty and the Alliance for the Defeat of Citizenship Taxation. citizenshipsolutions.ca
Information presented is NOT intended or offered as legal or accounting advice specific to your situation.
*****
Someone on the U.S. House Appropriations Committee puts the tiniest bit of pressure on Treasury regarding FATCA

Last week, Congress published H.Rept. 624 on the Financial Services and General Government Appropriations Bill (H.R. 5485). One paragraph in the report shows a slight concern for our issues. CTRL+F for “Foreign Account Tax Compliance Act”, or see p. 26 of the PDF:
Foreign Account Tax Compliance Act.—No later than 180 days after enactment of this Act, the Department of the Treasury shall submit a report to the Committees of Appropriations of the House and Senate on its decision (TD 9610 (78 FR 5874)) and TD 9657 (79 FR 12811)) to require withholding on non-cash value insurance premiums, including payments by foreign insurance brokers. No later than 180 days after enactment of this Act, the Committee directs the Government Accountability Office to determine the impacts of FATCA on United States citizens living abroad and make recommendations on FATCA implementation.
The Appropriations Committee could have done much more than this, such as prohibiting any of the appropriated funds from being used to implement FATCA. (Indeed, they did prohibit the funds from being used for far higher-profile Homeland causes célèbres, such as determination of tax-exempt status of non-profit organisations.) On the other hand, at least it’s a bit of progress from House Republicans’ earlier inattention to the issues of U.S. persons in other countries, such as last year when they voted nearly-unanimously to blow a giant hole in their own budget and repeal the estate tax while leaving the estate-tax-backstop § 2801 in place — which would have given Homelanders who leave $15 million or $15 billion to their kids a lower tax rate than emigrants who leave $15,000 to their kids.
If the executive branch’s past attitude towards deadlines is any guide, it will take far longer than 180 days for this report to get written. In June 2014, for example, the Senate Appropriations Committee directed DHS to report within 90 days on their efforts to implement the Reed Amendment. DHS’ report, discussed here at Brock, was finally published 350 days after the passage of the relevant bill.
And of course, when the report finally does come out, it will consist entirely of boilerplate lies about how FATCA doesn’t have any negative impacts on United States citizens living abroad (and even if it does it’s your own fault not the government’s fault, and even if it is the government’s fault it’s justified because of “tax evasion”, and even if the alleged individual international tax gap is utterly miniscule compared to the domestic tax gap the United States must do something and FATCA is something therefore it’s a Good Thing).
Conclusion
This is not a development that should cause any Brock readers to change their good plans. If you were planning to go get a CLN, keep that appointment at the consulate — it’s absurdly hard to get another one. If you were planning to continue your ordinary law-abiding life outside of the United States without obtaining a CLN, keep on keeping on. But if you think you’re U.S. tax compliant and have nothing to worry about, well, you’re lying to yourself — and even after this useless report comes out, you’ll still be lying to yourself.
CANADIAN FATCA IGA LITIGATION: We are still seeking additional CANADIAN citizen witnesses
WITNESS SEARCH UPDATE FOR CANADIAN FATCA IGA LAWSUIT:
WE STILL SEEK MORE CANADIAN WITNESSES:
Have you experienced marital stress or breakup, or medical or psychiatric illness because Canada turned you and your family over to a foreign country — or because you were afraid and entered into IRS compliance and suffered harm, or because you are in “hiding” and can’t afford to be IRS compliant or to renounce? Be a witness.
Thanks to Bruce Schneier, IRS quietly retracts two grossly insecure FATCA XML encryption & processing recommendations (but doesn’t admit fault or give credit)
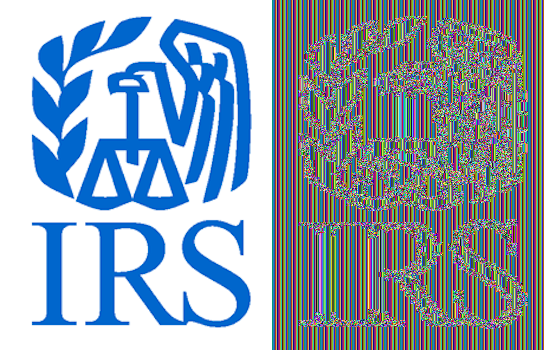
First, as renowned computer security expert Bruce Schneier first noted in February 2015 (and as we discussed last June), the IRS previously recommended that non-U.S. financial institutions use the insecure ECB mode of AES to encrypt FATCA data before uploading it to the International Data “Exchange” Service (IDES). The above image portrays the IRS’ logo encrypted using the IRS’ recommended settings. Several IDES users pointed out their concerns with that recommendation, but the IRS ignored them, and added the following to the IDES Technical FAQ (the date stamp in later versions of the FAQ falsely claims this was added in June 2015, but the question and its answer actually appeared on the IRS website as early as April):
E15. I read in a recent cybersecurity blog that there is a concern the encryption standards being used for FATCA data are no longer current. Is this correct?
No. The encryption process used to protect your FATCA data was assessed by the IRS prior to granting FATCA-related information technology systems the authority to operate. The IRS also assessed a number of security controls which are documented in NIST Special Publication 800-53 Revision 4. The IRS would not have approved IDES for use in transmitting tax information otherwise.
Second, as covered here last year, the IRS recommended that financial institutions having trouble due to a bug in IDES should submit their XML files to totally-unencrypted online tools in order to reformat them prior to IDES upload:
D13. I uploaded a FATCA Report to IDES 3 days ago and have not received a notification about the status of my FATCA Report. Does the XML format cause a problem?
The IRS has identified a specific scenario where notifications are not issued to filers when certain errors are present. A possible cause for a missing notification is XML that is not formatted and is contained on one continuous line. In this scenario, you can reformat the XML into an acceptable format using a variety of online tools, such as XML Pretty Print. The correctly formatted version of the XML can be resubmitted in a new data packet.
As of June 2016, both of these recommendations have been removed. D13 is totally gone and flushed down the memory hole with no acknowledgement of having been there. E15 is also now gone, but a new question E19 appeared in late March 2016, in which the IRS claim to have come up with the idea of fixing their absurd encryption recommendation all on their lonesome after a “routine security review”, with no credit whatsoever given to Schneier:
E19. We heard the IRS is changing the AES encryption cipher mode used during data packaging. What is this change?
The encryption standard used by the IRS meets current ISO standard(s). We continuously evaluate encryption algorithms to improve data security. During a routine security review, the IRS decided to improve encryption by replacing the Electronic Code Book (ECB) cipher mode with the Cipher Block Chaining (CBC) cipher mode. CBC is a stronger algorithm for encrypting data and its adoption will improve the current secure data packaging process. CBC requires an Initialization Vector (IV) for data packaging. Review the IDES Resources web page for more information
I wonder how many financial institutions will change their code to use CBC instead of ECB, but will leave the initialization vector on the all-zeroes setting previously recommended by the IRS (even though setting an IV at all should have been entirely unnecessary back then, as ECB doesn’t use it). If so, that will effectively nullify the benefits of switching to CBC.
I recall that the XML Pretty Print recommendation continued to appear on the IRS website earlier this year. Unfortunately, the Internet Archive did not automatically save any snapshots of the FAQ this year, and I didn’t remember to save it myself manually until today. The most recent previous Internet Archive snapshot is from September 2015, when both E15 and D13 still appeared. Question B11 makes reference to an “April 2016 maintenance release” of IDES; that release may have quietly addressed the line-length bug which caused the IRS to suggest XML Pretty Print as a work-around.
Ironically, XML Pretty Print is operated by a Canadian. I emailed him to point out the issue last year and he replied, but I didn’t hear back from him to get his permission to quote him for these posts.
WHILE PARLIAMENT SLEEPS: TAX TREATY PRACTICE IN CANADA
UPDATE – June 14, 2016
The following items were kindly provided by Allison Christians; sources for this paper:
Questions Submitted
NB: notice 3 different dates for when the house was aware of the IGA exemption to tabling policy
Reposted with permission of the author
WHILE PARLIAMENT SLEEPS: TAX TREATY PRACTICE IN CANADA
Allison Christians*
10 J. PARL. & POLITICAL L. 15 (2016).
 ABSTRACT
Canada’s Parliament plays little but a perfunctory role in the adoption of tax treaties, even though these agreements have significant impact on Parliamentary autonomy over core national budgetary matters as well as core legal and administrative functions. This article argues that Canada’s tax treaty process reflects a studied and intentional preference against public engagement in international fiscal policy, and that this stance has a negative impact on the rule of law. The article demonstrates the governance issue posed by lack of meaningful Parliamentary oversight using a recent departure from stated treaty policy, namely, the passage of a controversial agreement to implement the Foreign Account Tax Compliance Act (FATCA), an aggressive and extra-territorial regulatory regime imposed on Canadian financial institutions by the United States. The article examines the implications of Canada’s approach to this and other tax-related agreements and concludes that a much more engaged and informed Parliament is vitally necessary to achieve integrity in Canada’s treaty process.
INTRODUCTION
Tax treaties are the means by which nations share the revenues generated by cross-border business and investment activities. By ceding jurisdiction to tax certain kinds of income according to international norms, tax treaties constrain legislators’ autonomy in setting national tax policy. Because Canada’s ratification process involves adopting tax treaties as domestic law, these agreements also create access to administrative and judicial procedures in Canada, and thereby introduce international legal processes and principles in the interpretation of domestic tax law provisions. We might therefore expect that Parliamentarians would pay close attention to the tax treaties that come before them. Yet, Parliament plays little but a perfunctory role, mechanically passing tax treaties with virtually no scrutiny even as these instruments have gradually expanded in scope and arguably shifted in purpose.
What explains Parliament’s minimal input on tax treaties despite the significant role they play in national tax policy? A plausible answer seems to be a settled history of foreign affairs being the sole prerogative of the Crown, coupled with a treaty policy that prioritizes procedural expediency in Parliament over the messy politics involved in greater deliberation. Applied to a technically complex area like taxation, the desire for expediency— and likely an unspoken but rational desire for those in power to conduct foreign affairs without impediment—may encourage successive governments to navigate tax treaties quickly through Parliament despite occasional pledges to align treaty-making processes with principles of democratic participation in lawmaking, and established processes that would facilitate such participation.
Taking the position that tax treaties have significant impact on Parliamentary autonomy over core national budgetary matters as well as core legal and administrative functions, this article argues that Canada’s tax treaty process reflects an unstated preference against public engagement in international fiscal policy, with a negative impact on the rule of law. It first documents recent tax treaty processes in the context of the broad precepts associated with the treaty power, drawing attention to deviations from established precedents and stated policies. It then demonstrates the governance issue posed by lack of Parliamentary participation using a recent and significant departure from stated treaty policy. Finally, it argues that following established treaty procedures could be a marginally more appropriate approach to tax treaty policy, at least to the extent it would reintroduce democratically legitimate legislative constraints on the executive even while preserving the Crown’s treaty-making prerogative. However, as the article concludes, a much more engaged and informed Parliament is vitally necessary to achieve integrity in Canada’s treaty process.
Continue reading
ADCT Submission to Global Forum, “You Pay for What You Don’t Get”

Cross-posting from Maple Sandbox and its original post at http://www.citizenshiptaxation.ca:
“You Pay For What You Don’t Get” Submission to Global Forum
The Alliance for the Defeat of Citizenship Taxation (ADCT) has made an excellent submission to the Global Forum on Transparency and Exchange of Information for Tax.
Written by “Mary Blackhill” and edited by Stuart and Laura Mestleman, You Pay For What You Don’t Get reports on CBT’s “extensive mismatch with the tax regimes practiced in the rest of the world, the impact on “Tax Cheats by Birth” and how CBT drains money from other economies throughout the world.
The paper shows how CBT is inconsistent with global norms, is inconsistent with human rights (and the United Nations Declaration of Human Rights) and why other countries should not be expected to assist the United States enforce U.S. tax demands.
This submission was sent to the Forum by ADCT with the following e-mail from John Richardson:
To Whom This May Concern:
The last five years have seen significant interest in taxation in general, international taxation, offshore accounts and the identification of all income that is properly subject to taxation.This interest has resulted in voluntary disclosure programs throughout the world, FATCA and the OECD Common Report Standard. The recent disclosure of the “Panama Papers” appears to have reinforced interest in collaboration in the fight against tax evasion.
http://www.reuters.com/article/us-imf-g20-tax-idUSKCN0XG1WM
All of this has resulted in a world that is working together, promoting automatic information exchange and a worldwide standard for what is “fair taxation”. A common goal presupposes agreement on the fundamentals of what is fair and just taxation.
Fair and just taxation requires that people pay taxes to the countries where they reside. This principle is reflected in the OECD common reporting standard. Fair and just taxation is undermined when the residents of a country are also required to pay taxes to other countries for reasons that are unrelated to the source of the income.
There are few countries that confer citizenship based on place of birth in that country. There are only two countries that impose taxation based on citizenship. The United States of America is the only country that does both. This means that the the United States, imposes taxation on individuals based on the immutable characteristic of a U.S. “place of birth”.
What this means is that the United States expects that every person in the world who was born in the United States (the primary way of obtaining U.S. citizenship”), is required to pay taxes to the United States on their worldwide income. The requirement to pay taxes includes the requirement to file massive information returns on their activities and income in their one’s country of residence. Furthermore, the complexity of the U.S. anti-deferral regime results in the imposition of punitive taxation and reporting on the pensions and retirement planning vehicles of other nations.
Many people who were born in the United States are citizens and residents of other nations (in many cases having no connection to the United States and not even speaking English). This is an incredibly unfair and unjust situation. Furthermore, while the United States has not signed the OECD Common Reporting Standard (which has a definition of residence for tax purposes) it is attempting to impose FATCA on the world (which allows the United States in its sole discretion to define who is a U.S. citizen).
To be clear, U.S. “place of birth taxation” impacts both individuals and the economies of sovereign nations (resulting in the extraction of capital from those nations).
Attached for your perusal is a research paper. I invite you to read this research paper which is an attempt to explain some of these issues.
We strongly urge you to consider the adoption of a standard of fairness in worldwide taxation. We urge you to clarify that this standard should be in opposition to taxation based on solely on having having U.S. citizenship conferred on somebody at birth. In other words: fairness in worldwide taxation means that individuals should be subject to taxation based on where they live and NOT where they were born.
I would welcome the opportunity to discuss these issues with you further.
John Richardson
Toronto, Canada
The Alliance For The Defeat Of Citizenship Taxation
JUNE 3, 2016 Canadian FATCA IGA Litigation Status Report Submitted to Case Management Judge
You (Canadian and International donor-supporters, witness volunteers and plaintiffs, Isaac Brock Society and Maple Sandbox who let me post on their websites) are all major investors in our Canadian FATCA IGA legislation lawsuit. The pace must seem very slow to you, but we do move forward. Here is a brief update:
This link provides the letter (a “status report“) our Vancouver litigator Joe Arvay sent to the Case Management Judge responsible for the “supervision” of our litigation in Canada’s Federal Court.
Below I also mention briefly what the upcoming Constitutional-Charter trial is about — our “Claims”, and what Government thinks of our Claims.
— The key points in our June 3 2016 status report:
CANADA REVENUE “Answers” to Key Questions on What FATCA Turned Over to US IRS and What CRA Got in Return From IRS in 2015
This was originally posted by Lynne Swanson on Maple Sandbox as “CRA Response (Sort Of) on FATCA ATI & Order Paper Questions”
For me, the key message is that CRA refused to answer key questions on the September 2015 FATCA turnover that were raised in a Parliament. Lynne says below for example: “And of course, CRA won’t tell us how many or types of records they received from IRS–citing confidentiality and secrecy requirements of the Treaty.”
The questions asked were:
Q-1072
– April 18, 2016 – Mr. Dusseault (Sherbrooke} – With regard to the exchange information between Canada and the United States {US) under the Foreign .Account Tax Compliance Act (FATCA): (a) how many individuals were reported in total and broken down by (i) Canadian citizens (ii) permanent residents of Canada, (iii) temporary residents of Canada; (b) how many individuals were reported, broken down by (i) individuals with Canadian addresses, (ii) individuals with US addresses, (iii) individuals with addresses in other countries; (c) how many accounts were reported, in total and broken down by (i) bank accounts {ii) credit union accounts, {iii) investment accounts, (iv) insurance accounts, (v) other types of accounts; {d) with respect to {c)(iii)~ what types of insurance accounts were reported; (e) With respect to (c}(v), what other types of accounts were reported; (f} of the accounts reported. how many were (i) under $50,000 US, (ii) between $50,000 and $1,000,000 US, (iii) over $1,000,000 US; (g) of the accounts reported, how many were (i) Registered Retirement Savings Account accounts (ii) Registered Education Savings Account accounts,(iii) Registered Disability Savings_Account accounts, (iv) Tax Free Savings Accounts accounts ;(h) of the accounts reported, how many were held jointly with one or more non US persons. broken down by type of account and indicating the type of relationship between the Joint account holder and the us person if it is known; (i) how·many accounts of organizations were reported to the IRS because a US person had signing authority, interest in; or other connection to the organization; (j) of the accounts that were reported. how many were (i) business accounts, (ii) professional accounts, (Iii) charitable or non-profit organization {iv)connected to other organizations, broken down by type of organization; (k) what agency. organization and individuals was the information provided to; (l) what measures were taken to ensure this information wlll not.be provided to any other agency, organizatiqn and indivlduals; (m) what measures were taken to ensure that information transmitted wil not be subject to identity theft. fraud, other criminal activities, or breach of privacy; (n) how many records did Canada receive from the US, in total and broken down by (i) individuals who live in Canada, (ii} individuals who live in the us, (iii) individuals who live in other countries, broken down by country; (o) how many accounts did Canada receive information about; (p) What type of information was in the records Canada received; (q) did Canada receive information regarding (i) income fr~m the accounts (ii) total assets in accounts (iii) account balances (iv) transactions. deposits and withdrawals, (v) account numbers, (vi): names of account holders, (vii) Social Insurance Numbers, (viii) other related information; (r} what type of information did Canada receive that was not provided by the us prior to the FATCA Intergovemmental Agreement and (s) when did Canada.receive the information?